Money still moves hand to hand.
Collections become a recurring human chase. The group depends on reminders, memory, and whoever is willing to carry the stress.
Bring your savings circle together. Track contributions, plan payout turns, and keep everyone on the same page with My Ajo App.
Built for the way we save together.
Meet the community @myajoapp ↗Traditional circles are trusted because they are social, local, and familiar. What breaks is the operating layer: cash collection, invisible history, unclear accountability, and no real system once groups grow beyond tight personal trust.
Collections become a recurring human chase. The group depends on reminders, memory, and whoever is willing to carry the stress.
Reliable members start from zero in every new circle, while bad actors can hide behind fresh introductions and vague stories.
Receipts, disputes, payout timing, and reminders all land on one person. That makes circles fragile long before demand disappears.
Without digital records and identity workflows, circles stay harder to formalize, audit, or connect to broader financial infrastructure.
The experience is meant to feel warm, clear, and ritualized for members while giving operators a much stronger sense of control behind the scenes.
My Ajo App is designed around recurring behavior, not one-off payments. Groups can define amount, sequence, timing, and contribution mode in a way that feels operational instead of improvised.
Trust is not just a feeling in the room. The product turns recurring behavior into a portable score, giving groups a way to see reliability before problems become expensive.
BVN, documents, and verification flows sit inside the product rather than outside the circle.
Contribution state, member visibility, and risk alerts move from memory into interface.
Alerts, trust visibility, payout controls, and risk-oriented workflows all exist to make circles feel less brittle. The goal isn't to strip away the culture — it's to keep the circle intact when pressure rises.
The product experience should feel clear even for members who are not looking for a complicated finance app.
Members enter a circle with clear visibility into amount, order, timing, and expectations.
Clarity firstTrust starts with better member certainty, not just introductions and chat messages.
KYC in flowOnce collection settings are linked, the circle relies less on chasing and manual coordination.
Recurring behaviorGood behavior becomes more visible over time, giving circles a stronger memory than gossip and screenshots.
Portable reputationWhen it's your turn, the payout should feel expected, not dramatic — the money is there, on schedule.
Your turn, paidAjo only works when the money is safe and the rules are clear. Here's how My Ajo App handles the hard parts — in plain terms, no fine print.
Every contribution is auto-debited on schedule, and a missed payment triggers instant alerts and a trust-score penalty. Payout order is managed so the group isn't left exposed. My Ajo App reduces default risk — it doesn't guarantee against it.
No. Ajo is a community savings circle, not an insured bank deposit. My Ajo App makes the circle transparent and accountable, but members save at their own risk.
Payments are processed by Paystack, which is licensed by the Central Bank of Nigeria. My Ajo App never holds or custodies your money — contributions move between members through regulated rails.
We verify identity with BVN and documents to keep circles safe, and we handle your data under Nigeria's NDPA. See our Privacy Policy.
The app is free to download. Before your first circle, a one-time ₦1,000 identity check (BVN and documents) keeps every circle safe. After that, you pay a 2% service fee per contribution (minimum ₦50), plus the standard card or bank-transfer processing fee — you'll always see the full total before you pay. Risk protection is an optional 1.5%.
Still have a question?
Chat with us on WhatsApp ↗These names describe related community savings traditions. In a rotating circle, members contribute regularly and take turns receiving the pot. Collection arrangements can differ, so agree your group's rules before you start.
Understand what an ajo savings app does, how to compare one and how to bring an existing circle online.
Choosing an Ajo savings app →Follow a worked example of contributions, payout turns and the commitment each member makes.
How Esusu works →Agree a contribution schedule, record who has paid and plan how your group will handle missed payments.
How to organise an Adashe group →Learn the difference between a rotating savings group and a collector who keeps individual savings records.
Osusu and Susu explained →My Ajo App is raising a focused pre-seed round to grow a live, instrumented product across web and mobile in Nigeria. We're pre-revenue by design — the full deck, product walkthrough, and forecast model are available on request.
For information only — not an offer to sell or a solicitation to buy securities. Raise terms are indicative and subject to definitive agreements. Any forward-looking statements are projections, not guarantees of future performance.
Payments, BVN/KYC, AML workflows, trust scoring, and full group flows already run in production on Paystack rails — tested with 40+ real users.
Built around shared financial behavior and operator workflows — which changes both the UX and the defensibility.
A 2% fee on each contribution, optional 1.5% risk protection, and admin subscriptions (₦2,000–₦5,000/mo). Lending stays on the roadmap.
At the standard 2% fee, one 8-member ₦60,000/cycle circle generates about ₦9,600 each cycle — ₦76,800 over a full rotation — before protection and subscription revenue.
28% of Nigerian adults — roughly 37 million people — save through a savings club or informal arrangement; 72% save, but only 38% save at a bank. That gap is the market. World Bank Global Findex, 2024
67.8m Nigerians now hold a BVN, ₦105 trillion moved over instant transfers in 2024, and there are 150m mobile connections — the identity and payment rails to collect and verify at scale. NIBSS · DataReportal, 2024–25
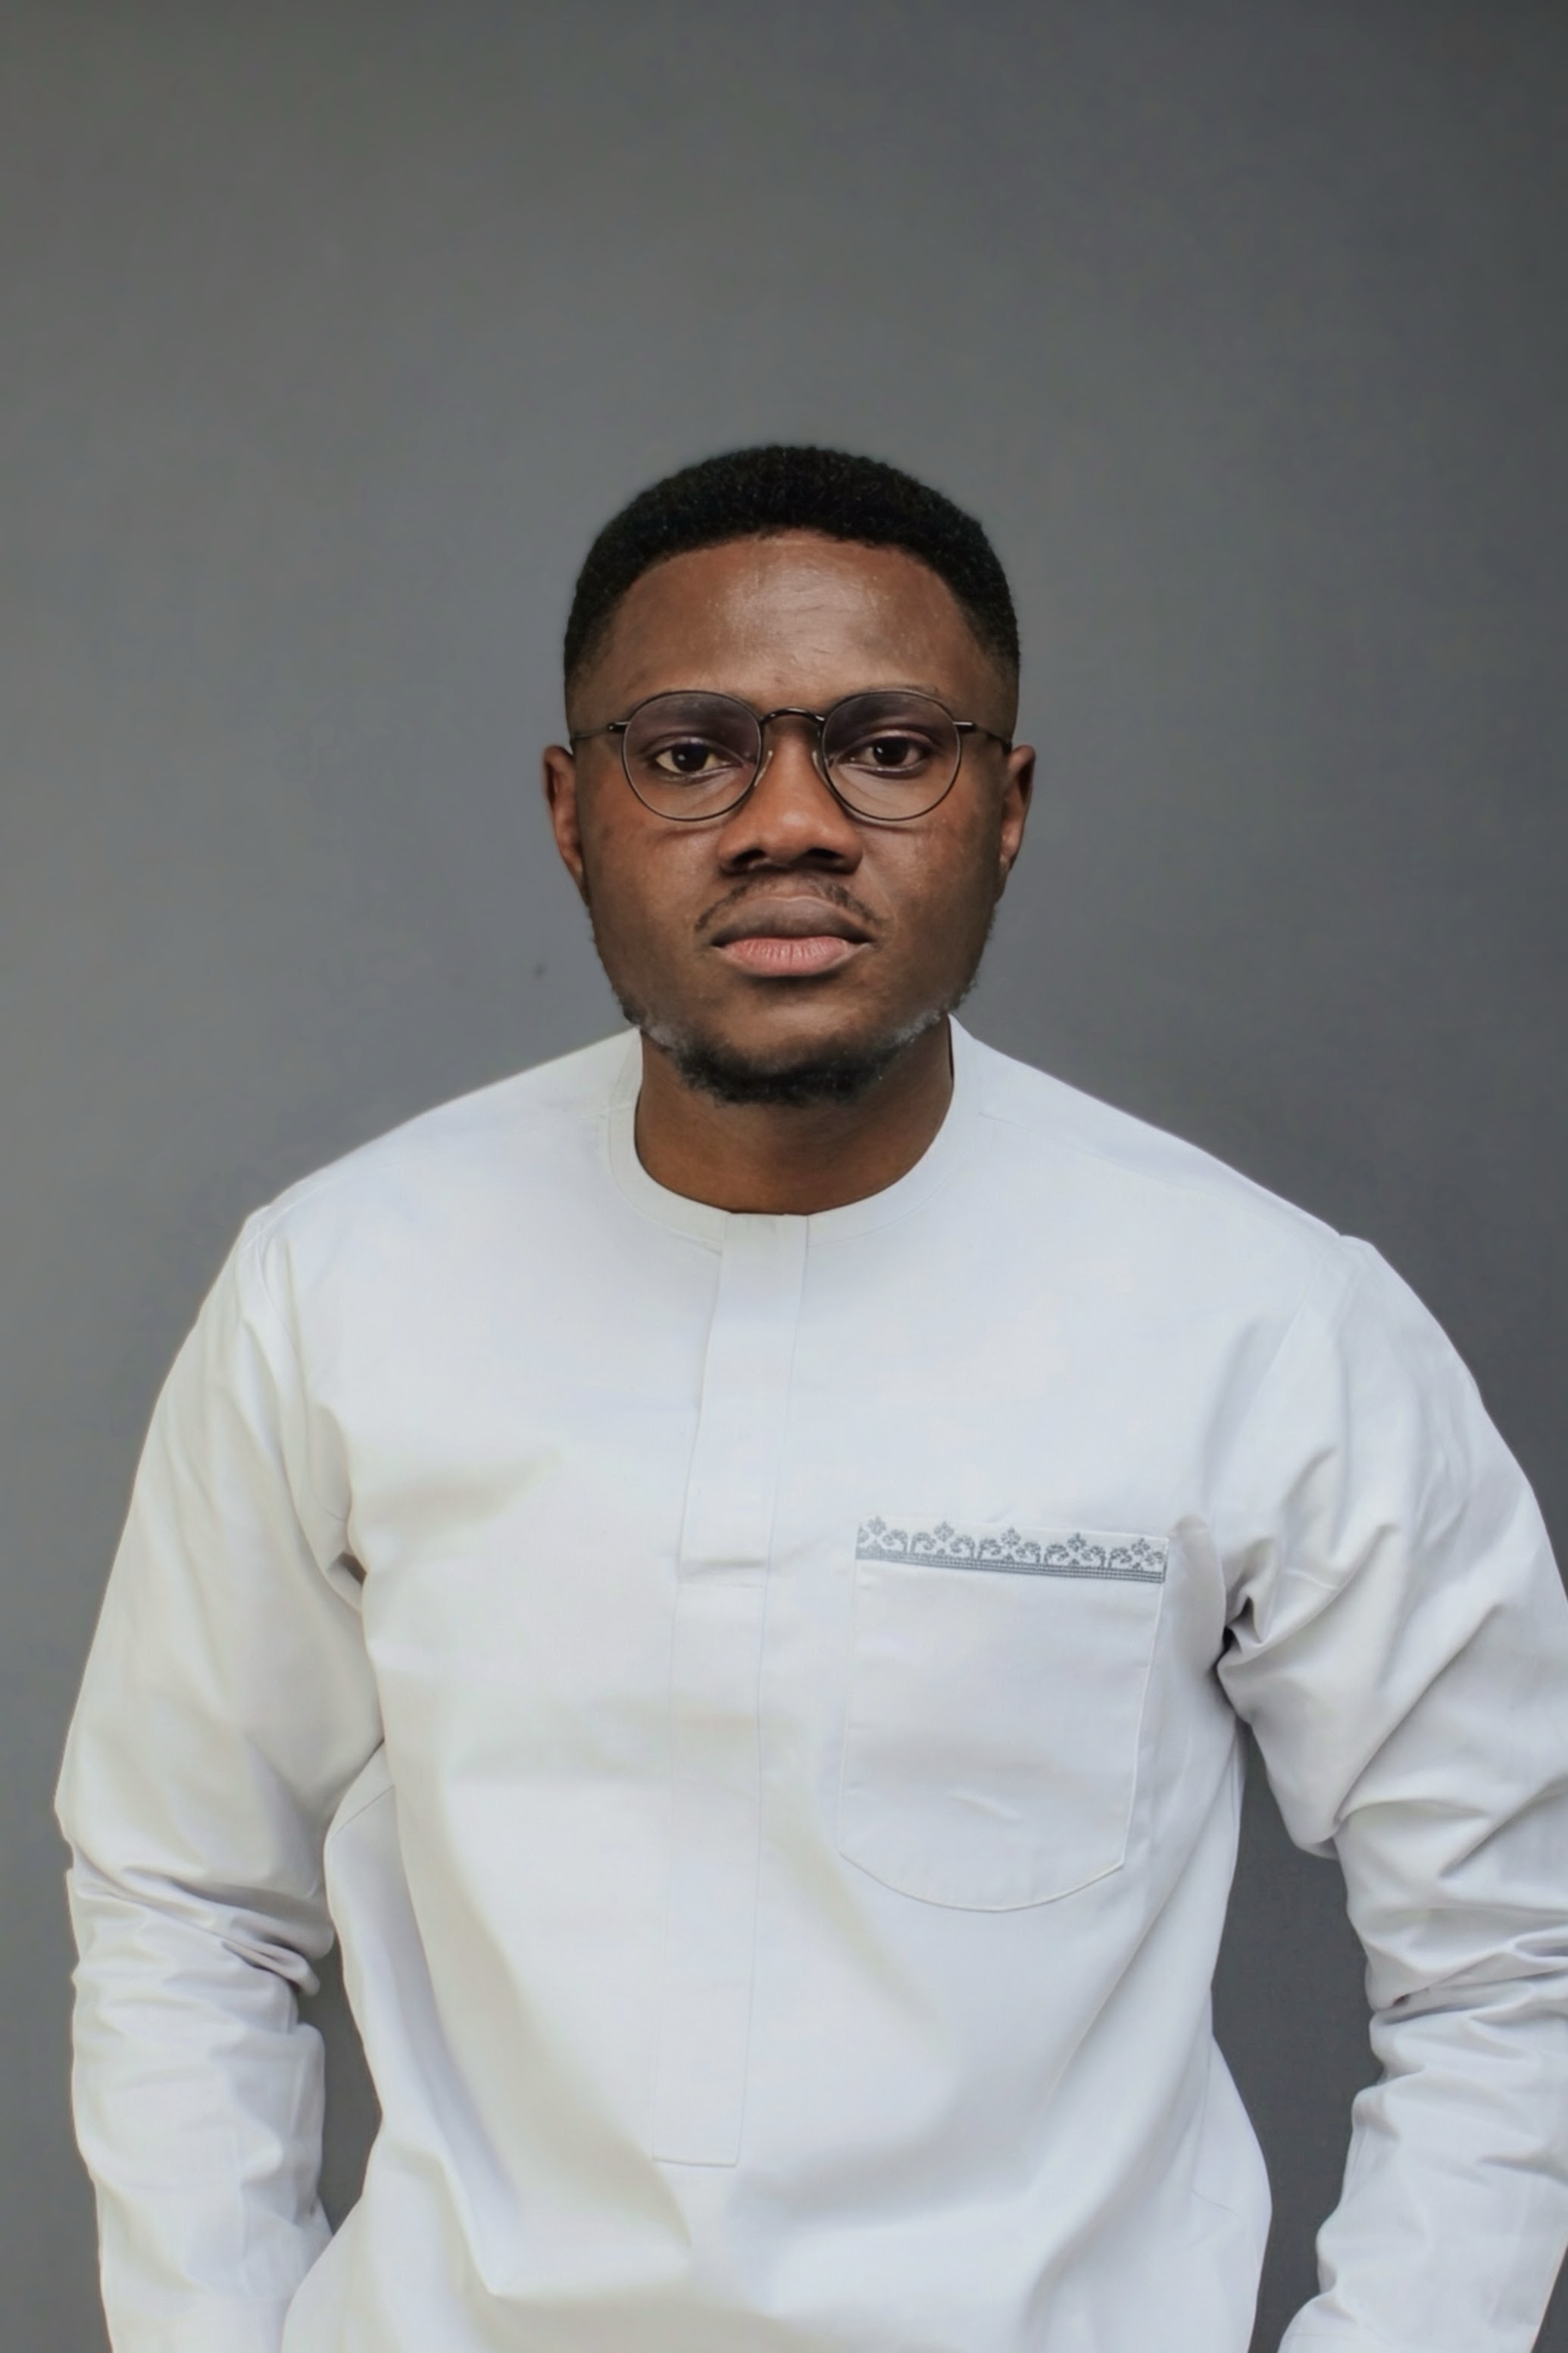 Founder / CEO
Solo technical founder. Personally designed and shipped the live stack end to end — Paystack payments, BVN/KYC, AML workflows, trust scoring, and the operator dashboard. Capital-efficient today; hiring after the raise.
Keep the warmth of the circle. Remove the confusion around the money.
My Ajo App is not trying to erase how these communities save. The point is to make the experience more legible, dependable, and scalable without flattening the social logic that made it work in the first place.